The most useful planner is the one that still makes sense on an ordinary, slightly messy day.
A flexible monthly budget starts with reliable income, essential commitments and irregular costs, then gives every remaining amount a job without pretending the month will be perfectly predictable. Build in a buffer and update actuals during the month.
The most useful planner is the one that still makes sense on an ordinary, slightly messy day. A flexible monthly budget starts with reliable income, essential commitments and irregular costs, then gives every remaining amount a job without pretending the month will be perfectly predictable. Build in a buffer and update actuals during the month.
Work through these in order the first time. Once the system is familiar, your regular review can be wonderfully short.
Begin here before you add anything optional. A clear starting point saves a surprising amount of rework later.
Keep this information together in one place. When the facts are easy to find, the next decision becomes much simpler.
Now shape the plan around what is actually available—your real time, tools, budget and capacity.
This is where the plan becomes flexible. Leave enough breathing room for the ordinary changes real life brings.
Do a practical check before moving on. Make sure the people, dates, quantities and access details still line up.
Finish with a simple review rule: keep what helps, remove what does not, and update only the part that changed.
A household expects two paydays but has a large insurance payment every six months. Dividing that payment by six turns it into a visible monthly sinking fund. If transport runs high, the plan draws from a named flex category rather than silently reducing savings or missing a bill.
Notice the pattern: the plan holds the useful details, but it still leaves room for a human day. That is the sweet spot.
Pause and return to the first decision. Clarity now is far more useful than extra detail built on the wrong assumption. Try this instead: Map bill due dates against expected income dates.
Bring this back to one trusted source of truth so you are not maintaining the same information in several places. Try this instead: Set realistic ranges for variable essentials.
Test the smallest workable version first. You can add more once the page has earned a place in the routine. Try this instead: Convert known annual costs into monthly sinking-fund amounts.
Add a reset point. A useful system should help you continue after a change, not make you feel as though you have failed it. Try this instead: Assign savings, goals and discretionary limits.
Use this as a cheerful final check—not another list you have to manage perfectly. If the important details are covered, you are ready to begin.
A flexible monthly budget starts with reliable income, essential commitments and irregular costs, then gives every remaining amount a job without pretending the month will be perfectly predictable. Build in a buffer and update actuals during the month.
Start with income timing, fixed commitments and variable essentials. Those choices shape the pages, level of detail and routine that will actually be useful.
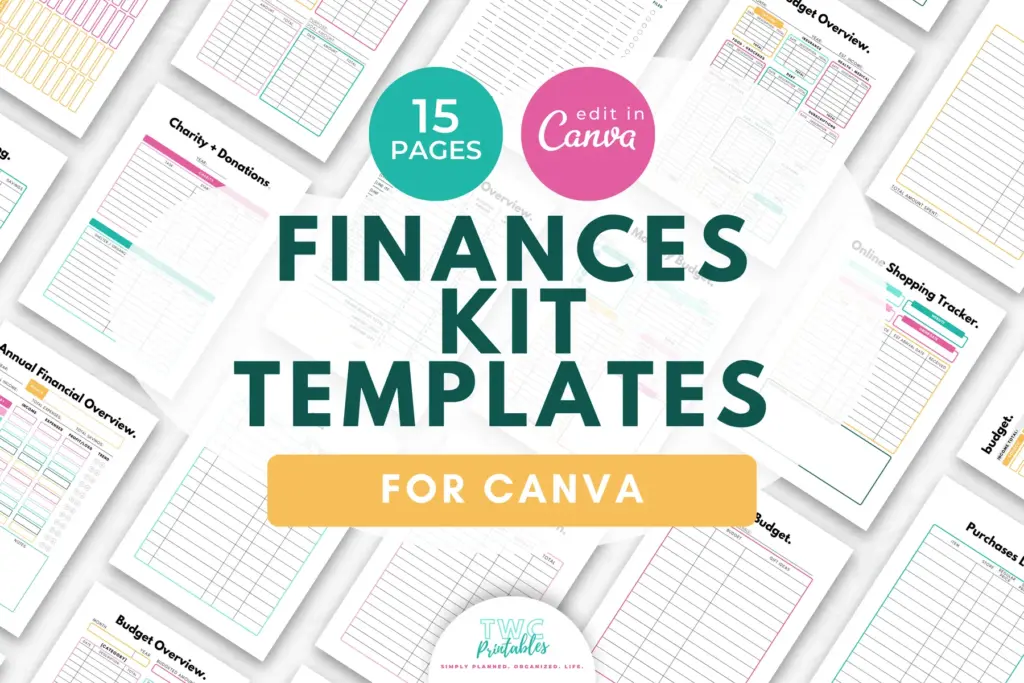
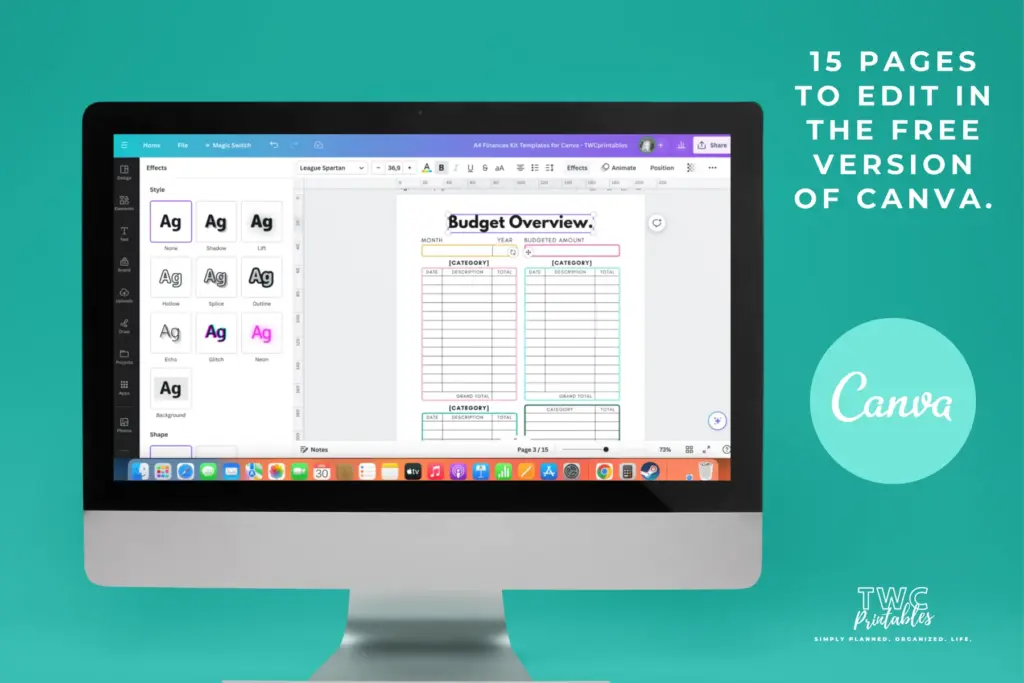
Yes. An editable Canva template can remove the layout work and give every important detail a clear home. Start with the pages you will genuinely use, customize the colours, fonts and wording, and leave optional pages out until they prove helpful.
Begin with collect recent income and spending records, map bill due dates against expected income dates and set realistic ranges for variable essentials. Use the smallest complete version for one real cycle, then keep what helps and simplify what does not.
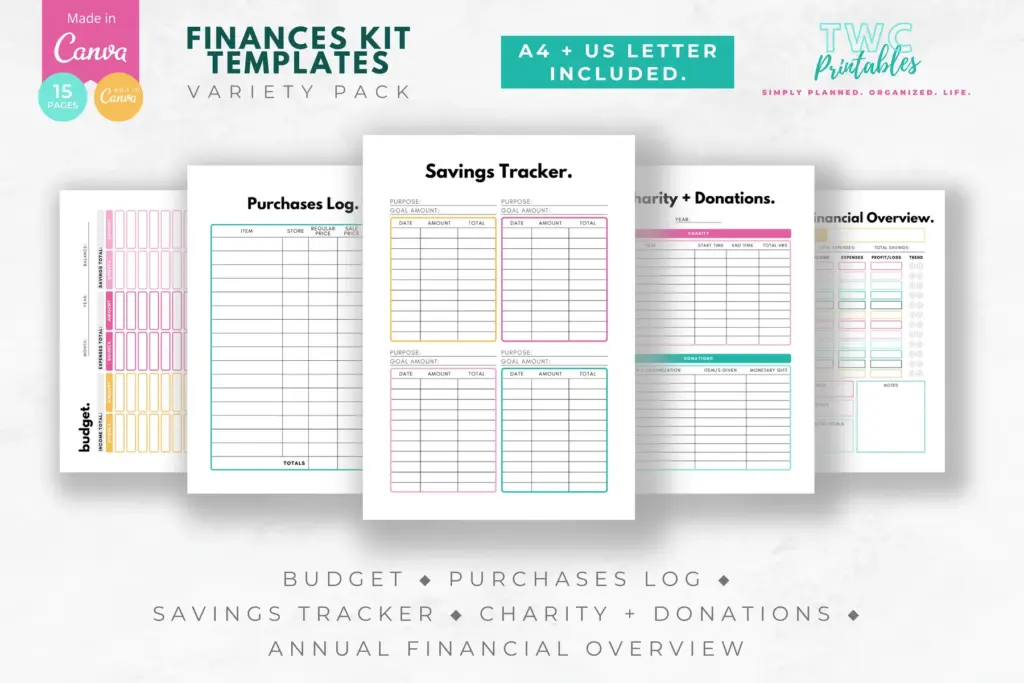
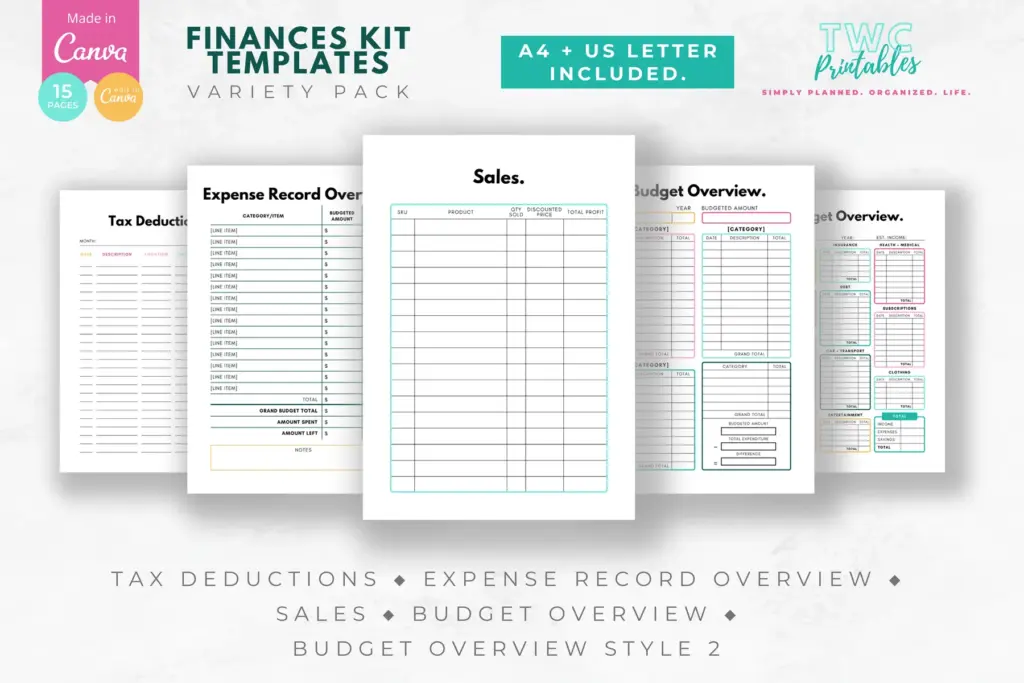
Turn the important numbers into a routine you can actually review with bright, editable finance-planning pages.
The sources below were reviewed for this guide on 26 August 2026. Platform features, prices, policies and legal requirements can change, so confirm the current official terms whenever a decision has legal, financial, health or account consequences.
Reviewed and updated by TWCprintables Editorial Team.